Life Insurance · Advanced Planning
Non-Variable Private Placement Life Insurance

How the structure differs
What It Is
Global Investment Strategies helps qualified business owners, real estate families, and multigenerational households evaluate whether a non-variable private placement life insurance structure belongs in their planning. These specialized permanent life insurance designs are considered by some families for estate liquidity, succession funding, and long-term legacy objectives.
A distinct contract design
Traditional private placement life insurance in the U.S. is generally a variable policy with separate investment accounts. The non-variable private placement approach GIS evaluates is a different contract design, used only with compliance-approved language and the specific carrier form. It is not a type of conventional variable PPLI.
Limits, risks, and eligibility
Any contractual crediting floor limits negative index credits in a given period. Policy charges, loans, and withdrawals can still reduce cash value. Neither structure is risk-free. Availability is generally limited to accredited investors or qualified purchasers with substantial resources, insurability, and a documented long-term need.
Watch the conversation
Watch: Doug & Jay on Non-Variable Private Placement
Short conversation on the difference between variable and non-variable designs, what a floor actually protects, and how GIS approaches a first review.
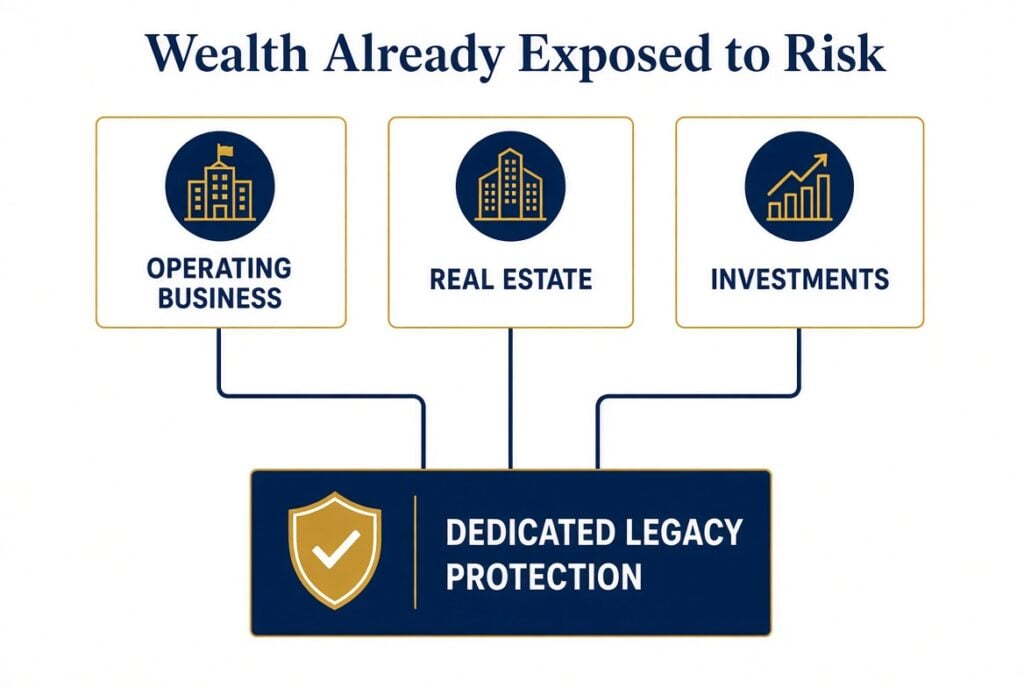
Conceptual only. Insurance is one possible resource alongside assets that already carry risk.
Common planning objectives
Why Families Explore It
To create a potential source of liquidity that does not depend on selling a business or real estate at the wrong time
To address succession, key-person, or buy-sell needs while the operating company continues
To support inheritance equalization or multigenerational legacy goals
To evaluate greater predictability for a portion of capital that sits alongside growth-oriented assets
Death benefits are often income-tax-free and cash-value growth is tax-deferred under current law. Estate, gift, and MEC questions require individual review with your advisors.
Who it fits
Who Typically Considers It
Business owners
Business owners with concentrated wealth in a closely held company
Real estate families
Real estate families whose net worth is tied up in property
Multigenerational families
Multigenerational families planning for equalization or long-term legacy capital
In Southern Arizona, many entrepreneurial and real estate balance sheets reflect exactly this kind of concentration.
Illustration · Inheritance equalization
Providing for both the operating and non-operating child
Example: A closely held business owner has one child active in the company and another who is not. The operating child wants to continue the business; the non-operating child needs fair value. A life insurance policy can be structured to provide liquidity for equalization without forcing a sale of the company at the wrong time. Results depend on ownership, existing agreements, and underwriting.
Funding pathways
How Funding Can Work
SOFR-Based Lending
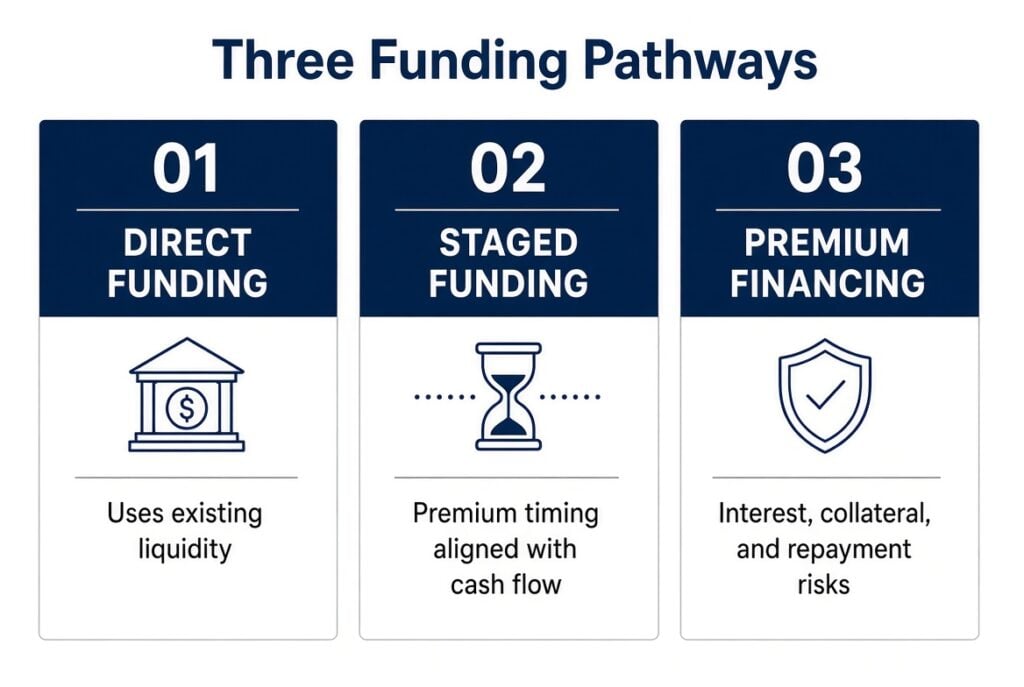
Premium financing adds interest, collateral, and repayment risks. Reduced cash outlay is not lower total cost.
01
Direct funding
Premiums paid from existing resources
02
Staged funding
Timing aligned with cash flow and contract rules
03
Premium financing
Lender-funded premiums (adds interest, collateral, renewal, and exit risks)
Our process
How a GIS Review Works
A confidential conversation
Confidential conversation about your objectives, existing coverage, and liquidity needs.
Coordination with your advisors
Coordination with your attorney, CPA, and other advisors.
Comparing carrier illustrations
If the strategy appears appropriate, comparison of carrier illustrations using only compliance-approved designs.
We begin with your balance sheet and goals. These cases are engineered—not simply sold.
What you receive when you book
- Educational guide covering the variable vs. non-variable distinction
- Clear explanation of what a crediting floor does and does not protect
- Overview of direct, staged, and premium-financing pathways
- Common family situations where liquidity and succession questions arise
Delivered with your confirmation email after you schedule.
Common questions
Frequently Asked Questions
How is non-variable private placement different from traditional variable PPLI?
Traditional private placement is generally variable and separate-account based. The non-variable approach is a distinct contract design. GIS uses only compliance-approved language for any comparison.
What does a crediting floor actually protect?
It may limit negative credited interest in a defined period. It does not prevent net cash value from declining due to charges, loans, or withdrawals.
Can this help avoid selling a business or property?
Potentially. Death-benefit liquidity can give a family more options and time. Results depend on policy ownership, debt, timing, and existing agreements.
Is premium financing risk-free or a guaranteed cost saver?
No. It introduces interest, collateral, renewal, and repayment risks. Reduced initial cash outlay is not the same as lower total cost.
Who should be involved?
A conversation, not a commitment
Request a Confidential Review
Schedule a conversation to determine whether a non-variable private placement structure deserves consideration for your situation. When you book, you will also receive our educational guide.
Schedule a Consultation(520) 360-8177 · glistrategies.com
It’s your life. Keep it yours.
Further reading
Learn More
Educational information only. Not individual investment, tax, or insurance advice. Policy availability and any financing are subject to underwriting and approval. The term “non-variable private placement” is used only as approved by compliance. Guarantees are limited to the contract and the insurer’s claims-paying ability. A crediting floor does not prevent net cash value from declining. Premium financing involves costs and risks. Consult your legal and tax advisors.